Death Doesn't Cancel Autopay
Someday after I die, my sons are going to have to go through my stuff, and I have to admit that I find this thought both amusing and a little terrifying. Not because I'm hiding anything particularly scandalous, or at least nothing they'll be able to prove, but because I know how much stuff I've accumulated over the years that makes perfect sense to me and will make absolutely no sense to them.
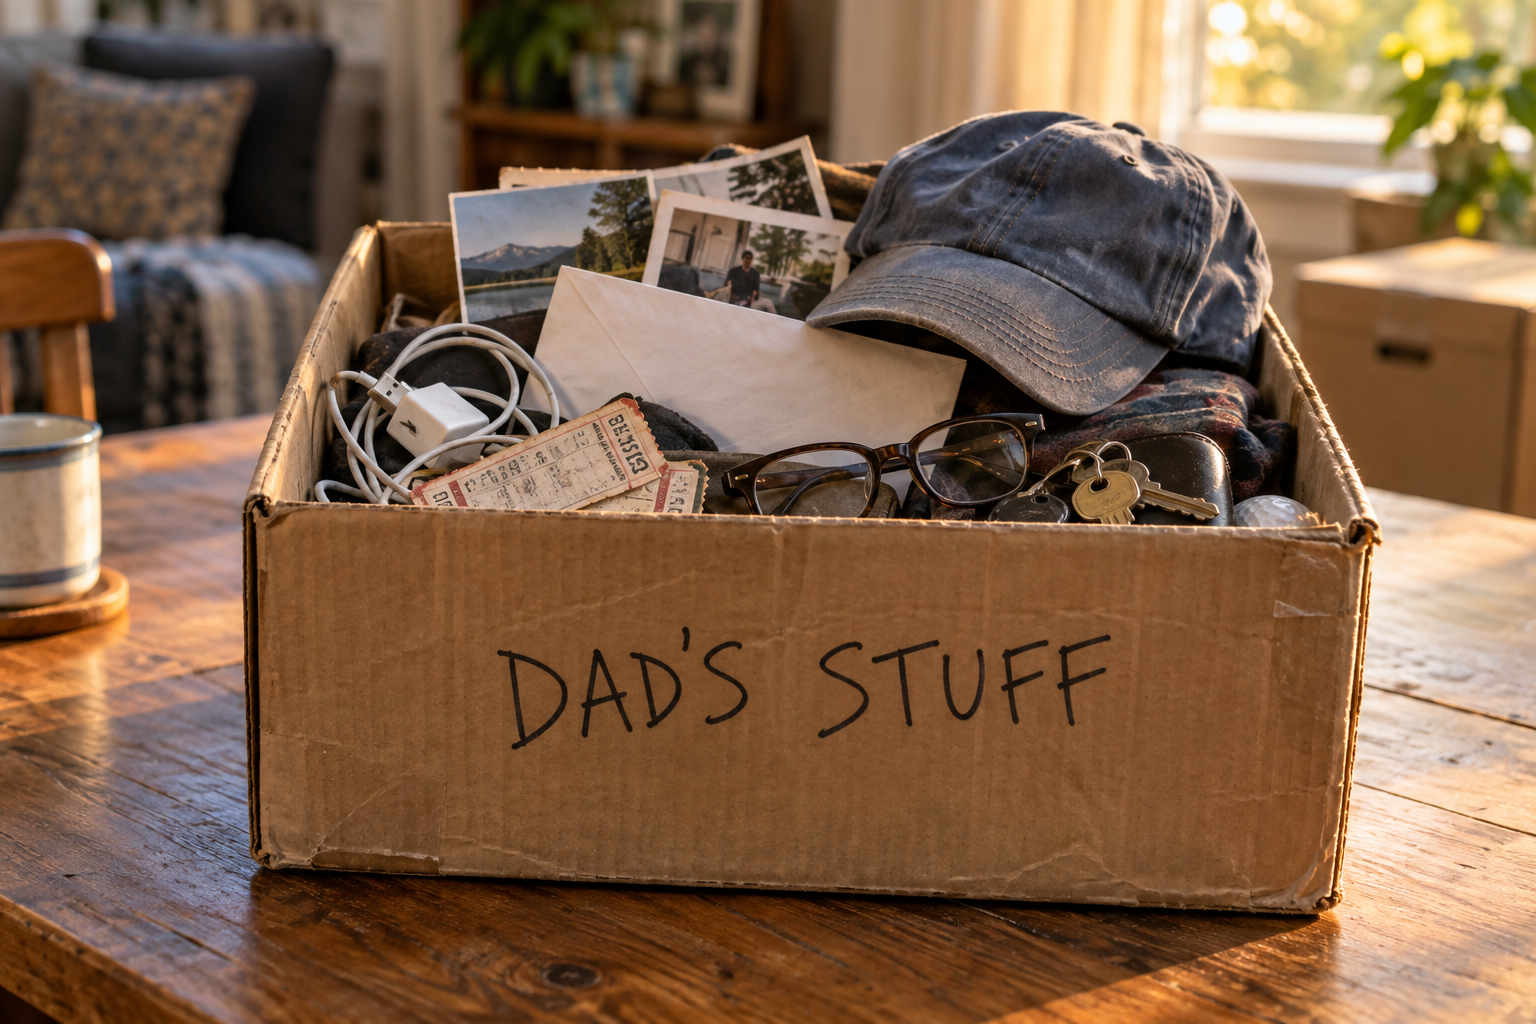
I can already picture it. One of them will open a drawer, pull out some completely inexplicable object and ask the other, “Do you have any idea why Dad kept this?” The answer will almost certainly be no. Eventually somebody will say, “We probably shouldn't throw it away,” and into a box it will go. That box will be labeled DAD'S STUFF and moved from closet to closet for the next twenty years because apparently one of the things we inherit from the people we love is the inability to throw away their weird crap.
That's funny when we're talking about old ticket stubs, charging cables, or whatever other treasures my children someday discover. It becomes considerably less funny when the thing they're trying to find is an insurance policy, a bank account, an important password or the answer to a very simple question: What did Dad want us to do?
I've spent enough time around death to know that dying leaves behind more than grief. It leaves behind an astonishing amount of administrative work, and unfortunately the electric company, Netflix and the HOA don't receive some cosmic notification that says, “Marty died Tuesday, please stop sending him bills.” The financial machinery of a person's life keeps humming along until somebody who is very much alive starts shutting it down.
That's something we don't talk about much when we talk about “final expenses.” We usually mean the funeral, and certainly that's part of it, but the funeral isn't the only bill that survives us. There is a strange stretch of time between someone's death and the moment their financial life finally comes to rest, and somebody has to live through that stretch.
Usually, that somebody is a person who loved us, and they're doing all of this while grieving. They may be planning a funeral while trying to figure out whether the mortgage has been paid, which bills are automatically drafted, how long the electricity needs to stay on and what accounts need to be closed. Someone may have to miss work or travel. There may be a car to sell, subscriptions to cancel or a dog that suddenly needs somewhere to live.
I've seen enough grief to know what it can do to an otherwise perfectly capable person. People forget things. They read the same piece of paper three times and still aren't sure what it says. They can make a dozen decisions at the funeral home and then become completely overwhelmed deciding what everybody should eat for dinner. Yet right in the middle of all that, we sometimes leave them a scavenger hunt. Where's the will? Did Mom have insurance? Who's the beneficiary? Where does Dad bank? What's the password? And eventually, “Why in God's name was he still paying $14.99 a month for this?”
The more I think about it, the more I wonder whether planning for our death is less about having everything perfectly arranged and more about simply leaving fewer questions.
Most of us aren't going to leave behind a beautifully organized binder with labeled tabs containing everything our family could possibly need. If you have one of those, congratulations. I admire you and also find you slightly suspicious. The rest of us can at least tell someone where the important things are, what we've already arranged and what we want done. And if we have life insurance, perhaps we should make sure the person we've named as beneficiary actually knows the policy exists.
That's also why I've started thinking differently about final expense insurance. Yes, it can provide money for a funeral or cremation, but it can also provide something less obvious: a little financial breathing room during that strange period when someone is grieving you while simultaneously trying to wind down the life you left behind.
It isn't supposed to turn someone's death into a payday, nor does everybody need a huge policy. It’s simply money that’s there when the person you chose as your beneficiary needs it, without you having to predict which expense is going to arrive first.
Maybe “final expense” is actually a misleading name because death doesn't come with one final expense neatly printed at the bottom of a receipt. It comes with bills, responsibilities, decisions and questions, and eventually the people who love us have to sort through all of them.
Someday my sons really will go through my stuff. They'll throw some of it away, keep some of it and probably find a few things that make them wonder what exactly was wrong with their father. I hope they laugh. I hope they find things that bring back stories and, for a moment, bring me back into the room with them.
But here's what I don't want. I don't want what I leave behind to become something they have to carry.
I can't spare them the grief of losing their father someday. There isn't an insurance policy in the world that can do that. But I can leave fewer questions, make a few decisions now instead of leaving those decisions to them and provide some financial breathing room for whatever that day brings.
Maybe that's what a loving legacy looks like. We can't make death easy for the people we love, but we can try to make what comes after it a little easier.
Because death doesn't cancel autopay.
But love can plan ahead.